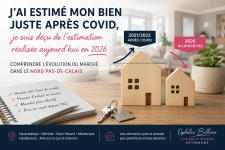
“My Property Was Valued Just After Covid. Why Is It Worth Less in 2026?”
“My property was valued at a higher price in 2021 or 2022. I’m disappointed with the valuation I’ve received today.”
I regularly hear this during appointments in Haverskerque, Merville, Saint-Venant, Morbecque, Hazebrouck, Aire-sur-la-Lys and the surrounding villages.
That disappointment is understandable. A property valuation directly affects your assets, future plans and sometimes the price you originally paid for your home.
However, a valuation is not a permanently guaranteed value. It estimates the price at which a property could reasonably attract a buyer at a particular time, taking into account market conditions, available financing and competing properties.
Between the period following the Covid lockdowns and 2026, these conditions changed significantly.
The Period Following the Covid Lockdowns Created an Exceptional Property Market
The years 2020, 2021 and part of 2022 were far from ordinary for the property market.
Lockdowns changed the priorities of many households. Buyers began looking for more space, a garden, a room for working from home or a house outside a major urban area.
These preferences increased interest in detached houses and rural or suburban locations. In parts of Hauts-de-France, buyers were willing to consider homes further from their workplace in exchange for more land, outbuildings or a larger living area.
This demand coincided with particularly favourable mortgage conditions. According to the French Prudential Supervision and Resolution Authority, ACPR, which operates within the Banque de France, average housing loan interest rates reached a historic low of 1.06% in December 2021.
For the same monthly repayment and loan term, buyers could therefore borrow considerably more than at the higher rates seen in 2026. This greater borrowing capacity helped support both sale prices and the valuations made at the time.
The ACPR also reported that existing home prices outside the Île-de-France region rose by 9% between the fourth quarter of 2020 and the fourth quarter of 2021.
A valuation made during that period may therefore have been reasonable when it was issued, without remaining valid several years later.
Property Prices Reached Particularly High Levels in Late 2022
The Notaires-INSEE price indices for existing homes show that prices reached particularly high levels in 2022.
For all existing homes in metropolitan France, the price index stood at 133.9 in the fourth quarter of 2022, compared with a provisional figure of 127.4 in the first quarter of 2026. This represents a decline of approximately 4.9%.
For houses outside Île-de-France, the corresponding INSEE index fell from 136.4 to 130.9 over the same period, a decrease of approximately 4%.
These figures do not mean that every house automatically lost 4% or 5% of its value. Changes depend on the location, property type, condition, energy performance, land and competing homes for sale.
However, they illustrate why a valuation made when prices were high should be reassessed before marketing a property in 2026.
The Biggest Change Has Been Buyers’ Purchasing Power
In May 2026, the average interest rate on new housing loans, excluding renegotiations, stood at 3.21%, before fees and insurance, according to statistics published by the Banque de France.
This was below the high levels recorded in early 2024, but still considerably higher than the rates available in 2021.
Consider a simplified example.
A household able to spend approximately €1,200 per month on mortgage repayments could borrow substantially more at an interest rate close to 1% than at a rate above 3%, assuming the same loan term and excluding insurance and fees.
Even when a purchase remains affordable, less of the household’s budget is available to pay for the property itself.
This affects how buyers approach their search. They may compare properties more carefully, negotiate more readily and pay closer attention to renovation costs, energy bills, insurance and maintenance.
A price that attracted a buyer quickly in 2021 might therefore no longer be affordable or acceptable to a similar buyer in 2026.
In Early 2026, Prices Were Broadly Stable, but Buyers Remained Selective
It would be inaccurate to say that the entire property market has collapsed.
According to INSEE’s publication on existing home prices in the first quarter of 2026, provisional, seasonally adjusted prices rose by 0.2% over the quarter in France excluding Mayotte. Over a year, prices were almost unchanged, increasing by 0.1% overall.
The picture differed by property type: apartment prices rose by 0.6% year on year, while house prices fell by 0.2%.
Outside Île-de-France, prices were unchanged over the quarter. House prices were also almost stable year on year, falling by 0.1%.
These figures suggest a more balanced market than during the earlier period of falling prices following the rise in interest rates. They do not describe every local market or establish a trend for the whole of 2026.
In practice, pricing still matters. Properties priced in line with their condition and local competition are better placed to attract buyers. Homes marketed using an outdated valuation may remain listed for months and face greater pressure during negotiations.
How Can You Assess Your Property’s Market Value in 2026?
A reliable property valuation should start with completed sales.
France’s official property transaction database, known as DVF, or Demandes de valeurs foncières, contains transaction information drawn from notarial deeds and cadastral records. It is published by the French public finances administration, the DGFiP, and updated regularly.
These records are a valuable starting point, but they require interpretation.
A recorded transaction price may cover several plots or buildings. The data does not necessarily reveal the interior condition, the quality of renovation work, nearby disturbances or any special circumstances surrounding the sale.
That is why I generally assess several sources of information together:
Recorded sales of comparable properties.
Properties currently on the market.
Properties that remain unsold.
Marketing periods.
Feedback from active buyers.
The specific features of the property.
The budgets buyers can realistically finance.
The asking price and marketing strategy should then take the owner’s plans into account. An urgent sale, a sale linked to another purchase and a sale with a flexible timetable may call for different approaches.
Your timetable can influence the selling strategy, but it does not, by itself, change your property’s market value.